Introduction
Many PT (limited liability company) owners know that dividends are subject to 10% PPh (income tax). Fewer know that this tax can be reduced to zero, and fewer still understand the full conditions.
This facility has been in place since the UU Cipta Kerja (Job Creation Law) and is regulated in more detail in PMK 18/2021 (Minister of Finance Regulation 18 of 2021). The essence is simple: domestic dividends received by individuals are excluded from income tax, as long as they are reinvested in Indonesia in specified forms and for a specified period.
In practice, this facility is often misunderstood. Some assume dividends are automatically tax-free. Some have already invested but are still taxed because they missed one administrative condition. Others do not use it at all, even though part of their dividends will not be needed any time soon.
This article explains how the facility works with a case study using concrete figures, the conditions that must all be met, the most common pitfalls, and how the facility changes the "salary or dividends" calculation we discussed previously.
Note: this article is educational and summarizes general provisions from tax regulations and official explanations from the DJP (Directorate General of Taxes). The figures in the case study are simulations based on simplified assumptions. This article is not a substitute for advice from a tax consultant. For application to specific circumstances, please consult a tax consultant or financial advisor.
How the facility works
Mr. Hendra is the owner and director of a PT with annual profit of IDR 3 billion. After deducting 22% corporate income tax (PPh Badan) of IDR 660 million, IDR 2.34 billion remains and is distributed as dividends through the RUPS (general meeting of shareholders).
Under normal conditions, these dividends are subject to a 10% final income tax (PPh Final), which is IDR 234 million. This tax is not withheld by the PT. Mr. Hendra must pay it himself no later than the 15th of the month after the dividends are received.
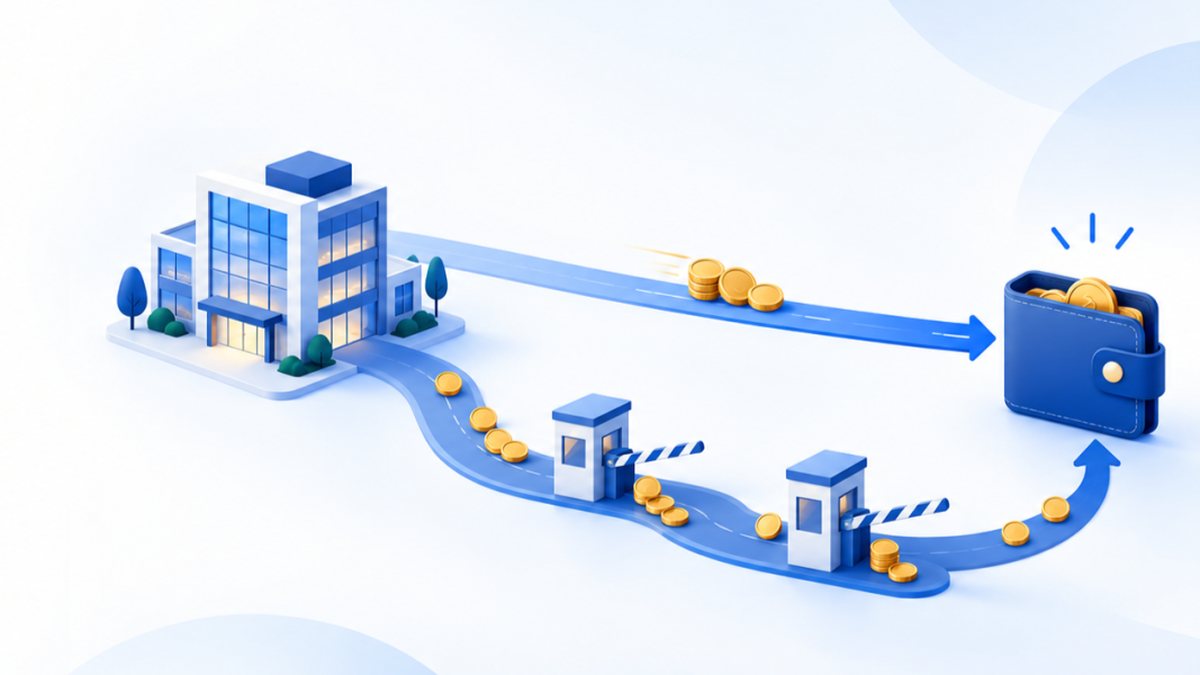
The exemption applies if the dividends are reinvested in Indonesia in accordance with the rules. The dividends are still distributed and received in Mr. Hendra's personal account. The difference is that the money is not spent on consumption, but placed in a form of investment set out by the government. If all conditions are met, the dividend tax becomes IDR 0.
The facility can also be used partially. If the dividends invested are less than the dividends received, the exemption applies only to the invested portion. For example, Mr. Hendra uses IDR 500 million to renovate his house and invests the remaining IDR 1.84 billion. The dividend tax payable is only 10% of IDR 500 million, which is IDR 50 million.
Permitted forms of investment
The forms of investment are set out in Articles 34 and 35 of PMK 18/2021. The list is fairly broad, but each form has limits to keep in mind.
Financial market instruments. These include government securities, bonds or sukuk issued by BUMN (state-owned enterprises) and private companies whose trading is supervised by the OJK (Financial Services Authority), shares, mutual fund units, and time deposits and savings. For placements in banks, the investment must be made at a bank persepsi, a bank appointed to receive tax payments, including Islamic banks.
Property. The investment can be in land and/or buildings, except property that receives a government subsidy.
Gold bullion. The gold must be 99.99% pure, produced in Indonesia, and accredited by SNI (Indonesian National Standard) and/or LBMA.
Equity participation. Dividends can be placed as equity in newly established or existing companies in Indonesia, as a shareholder. Direct investment in the real sector must take the form of equity participation in a limited liability company. Lending funds to a company does not fall under this form.
Other forms. The rules also cover infrastructure investment through public-private partnerships, real sector investment based on government priorities, cooperation with an investment management agency, and loans to micro and small businesses.
What about your own company? The DJP has stated that dividends reinvested in your own company are not prohibited, because PMK 18/2021 does not specifically prohibit it. This means an owner can receive dividends and then inject them back as additional capital for the PT's expansion. Because this explanation was given through a DJP service channel and is not explicitly written in the regulation, it is best to confirm its use with a tax consultant first.
Three conditions that must all be met
This facility is cumulative. Failing to meet even one condition makes the dividends taxable again.
First, the placement deadline. For individuals, the investment must be made no later than the end of the third month after the end of the tax year in which the dividends were received. Dividends received in 2026 must be invested no later than 31 March 2027.
Second, the investment period. The investment must be held for at least three tax years, counted from the tax year in which the dividends were received. During that period, the investment may be moved, for example from a time deposit to government securities, as long as it stays within the permitted forms of investment. What is not allowed is withdrawing the funds for spending.
Third, the investment realization report. The dividend recipient must submit an investment realization report electronically through Coretax (the DJP's tax administration system), no later than the end of the third month after the tax year ends. This report is submitted every year until the third year. In addition, the exempt dividends must still be reported in the SPT Tahunan (annual tax return) as income that is not a tax object.
The most common pitfalls
Of the three conditions, the third is the one most often missed. Business owners who have been disciplined in placing their funds feel their obligation is done, when in fact the realization report must still be submitted every year.
The consequences are significant. If the report is not submitted, the exemption may be voided and the 10% dividend tax becomes payable from the time the dividends were received, even though the money was invested in accordance with the rules. In Mr. Hendra's case, this administrative oversight is worth IDR 234 million.
The second pitfall is cashing out the investment before three years because of an unexpected need. For this reason, the funds allocated to this facility should be funds that will not be needed during that period.
How it affects the salary or dividends decision
In our previous article, we compared two ways a PT owner can take profit: through a salary as director, or through dividends. On a profit of IDR 3 billion with 22% corporate income tax, the dividend route carries a burden of 29.8%: 22% at the PT level plus 10% of the remainder. The owner's salary is only cheaper as long as its bracket rate stays below that figure, and the optimal point is around IDR 46.7 million per month.
If the dividends are reinvested, the burden on the dividend route falls to just 22%. As a result, salary that has already entered the 25% bracket becomes more expensive than dividends. In the same case, total tax with a salary of IDR 25 million per month becomes IDR 624 million, lower than with a salary of IDR 50 million per month, which reaches IDR 634 million. The optimal salary point falls to around IDR 310 million a year.
For small profits, the effect is barely noticeable. On a profit of IDR 100 million with the Article 31E facility, the reinvested dividend route still carries 11% corporate income tax, or IDR 11 million. That is still far more than the salary route at only IDR 2.05 million, because the owner's salary benefits from the non-taxable income threshold (Penghasilan Tidak Kena Pajak). The reinvested dividend facility is most relevant for businesses whose profits are already large.
The implication is that the owner's salary decision and investment plans need to be discussed together. Money for living expenses makes more sense taken as salary. Money that will genuinely be reinvested can be more efficient taken as dividends.
Closing
The reinvested dividend facility does not make dividends a free pass on tax. The owner trades the freedom to use the money for a 0% tax rate, and that trade is only valid if all conditions are met, including the administrative obligation that recurs over three years.
That is why the most important step actually happens before the dividends are distributed: separating the money that will be spent from the money that can sit untouched for three years, and then preparing a schedule for placement and reporting.
A healthy business is not just one that makes a profit, but one that understands its numbers, controls its risks, and moves in a clear direction.
References
- Forms of dividend investment (Article 34), placement instruments including the non-subsidized property condition, 99.99% gold bullion produced in Indonesia and certified by SNI and/or LBMA, and equity participation in a PT (Article 35), as well as the placement deadline, the minimum holding period of three tax years, and the prohibition on transfers other than to permitted forms of investment (Article 36). PMK 18/PMK.03/2021, copy of the regulation text, klikpajak.id/wp-content/uploads/2019/01/18_PMK.03_2021.pdf.
- Official overview of investment forms, including financial investment at a bank persepsi, the holding period, and the obligation to submit an investment realization report. Directorate General of Taxes, pajak.go.id/sites/default/files/2021-04/Peraturan Pelaksanaan UU Ciptaker (PP 9 Tahun 2021 & PMK 18 2021).pdf.
- Domestic dividends received by individuals are excluded from income tax if invested; if not, the 10% final income tax is self-paid no later than the 15th of the following month; the exemption applies only to the invested portion; the latest provisions are in PMK 81/2024 Articles 370 to 374. DDTCNews, news.ddtc.co.id/berita/nasional/1817052 and news.ddtc.co.id/berita/nasional/1811981.
- Investment realization reporting through Coretax, the cumulative nature of the conditions, and the risk of losing the facility if it is not reported. Pajakku, pajakku.com/artikel/dividen-bebas-pajak-10-syarat-cara-lapor-dan-risiko-lalai-administrasi.
- Dividend investments may be moved between forms of investment but may not be cashed out during the holding period. DDTCNews, news.ddtc.co.id/berita/nasional/42136.
- DJP explanation that dividends reinvested in your own company are not prohibited, as long as the provisions are met. DDTCNews, news.ddtc.co.id/dividen-diinvestasikan-di-perusahaan-sendiri-dapat-pembebasan-pajak-43060.
- Individual income tax brackets under Article 17 of the UU PPh (Income Tax Law) as amended by the UU HPP (Harmonization of Tax Regulations Law), which form the basis of the owner's salary simulation. Directorate General of Taxes, pajak.go.id/en/node/90251.
This article summarizes general tax provisions for educational purposes and is not a substitute for advice from a tax consultant. The figures in the case study are simulations based on simplified assumptions and do not yet include BPJS (social security) contributions. For decisions on specific circumstances, please consult a tax consultant or financial advisor.